Safeguarding the smaller investors
 0 Comment(s)
 Print
 E-mail China Daily, May 11, 2015


Despite last week's sudden decline of the Shanghai Composite Index, the recent bull run is not merely a temporary blip, and retail investors face some difficult choices, economists said.
 |
|
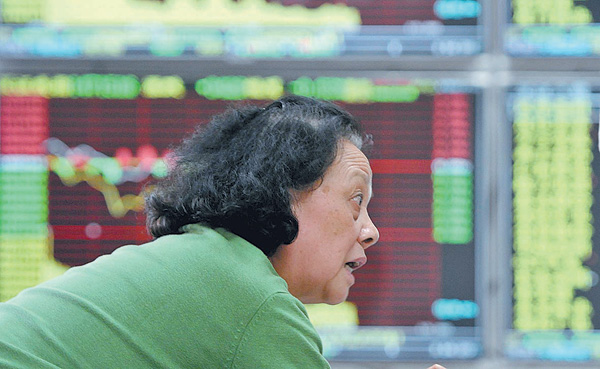
A stock investor at a brokerage in Jiujiang, Jiangxi province. She was shocked by the fluctuations in the A-share market. [Photo/China Daily] |
Liu Jipeng, an economist at China University of Political Science and Law, said that small traders will need to be on their toes when investing in the market.
"In China, stock prices are usually influenced by policy or other information that is difficult for retail investors to notice, such as companies' restructuring plans. The regulatory mechanism of information disclosure remains weak," said Liu. "Without specific legislative guarantees, it is difficult to ensure that the interests of small investors are adequately protected."
One of the most important legislative plans for China this year is the revision of the Securities Law, a legislator said during the annual session of the National People's Congress in March.
According to Yin Zhongqing, deputy director of the NPC Financial and Economic Affairs Committee, the NPC's Standing Committee reviewed the draft in late April, but it didn't disclose the details. If all goes well, the final draft will be published this year.
This time, protection of retail stock investors will be written into the Securities Law.
It will add a chapter setting out the principles of retail investor protection, including the investor eligibility system, a pre-lawsuit compensation system, and a cash bonus distribution system.
The revision of the law will also improve the lawsuit system, said Yin.
The Securities Law has been revised four times since it was created in December 1998.
"Compared to previous revisions, the draft will be a comprehensive overhaul, adding more than 100 clauses, amending more than 100 clauses and deleting more than 20 clauses," said Yin.
The draft will also reform stock and registration issues, strengthen supervision, cancel administrative approval for seven items and increase punishment for violators, according to the NPC deputy.
The amendment of the Securities Law has been viewed as the legal foundation for China to push forward the registration-based system for initial public offerings, one of the most important reforms of the capital market.
Prior to the reform, the existing stock issue method lacked an accountability system, which led to blind speculation for new shares, especially among retail investors, said Su Peike, a researcher with the Public Policy Research Institute at the University of International Business and Economics in Beijing.
Su said that the country's top securities watchdog, the China Securities Regulatory Commission, should scrap the system under which it is required to grant administrative approval for new offerings, but instead supervise whether listed companies disclose information in a timely and accurate manner.
Listed companies and their underwriters should both take responsibility to ensure information transparency, which is the key to protecting investors' interests, then the A-share market can be changed from its current role as a "cash dispenser for big enterprises", the researcher added.
In addition, the revision of the law will expand the business scope of securities firms and reduce administrative approvals for domestic companies to issue securities overseas.
Too much administrative intervention in the market is seen as the main factor distorting stock prices, which ultimately harms small and medium-sized investors, said experts.
Discussion about the reform has been going on for years, but no substantial progress had been made before the revision of the Securities Law.
This law was first introduced in 1998, clarifying the basic regulatory system for the stock market for the first time since the Shanghai Stock Exchange opened in 1990.
In October 2005, the NPC Standing Committee announced a comprehensive revision of the law, adding a sponsor system to take responsibility for listed companies' behavior.
The committee also revised provisions of the law in August 2004 and June 2013.
As the economic environment has changed a lot, further revision of the Securities Law is necessary as an important part of the overall national financial reform toward a more market-oriented system, said Xin Chunying, vice-chairwoman of the NPC Legislative Affairs Committee.
"There are some international rules for drafting securities laws, but they are not yet reflected by the law in China, as the market is not mature," she said.
The core concept of the Securities Law should be investor protection, Xin said.
CSRC Chairman Xiao Gang, in an article on the commission's website, said that policymakers are considering launching a public lawsuit system for the security market, under the framework of the revised law.
This means there would be a special organization to initiate public prosecutions when individual investors suffered losses from illegal activities including disclosing false information, insider trading and market rigging, the official said.
Any mechanism that hurts market fairness and justice, or tends to trigger regulatory arbitrage or lead to systemic financial risks, should be improved. Such problems need to be solved through the law revision this time, said Xiao.
Market facts
Nov 26, 1990: The Shanghai Stock Exchange is launched, the first in the mainland.
July 3, 1991: The Shenzhen Stock Exchange opens.
July 1, 1999: China's first Securities Law is brought in. Initial public offerings have to undergo an approval procedure.
May 17, 2004: The China Securities Regulatory Commission establishes a small and medium-sized enterprises board at the Shenzhen Stock Exchange. This has a lower threshold for IPO listings than Shanghai.
Aug 28, 2004: The Standing Committee of the National People's Congress, the nation's top legislature, revises part of the Securities Law.
Oct, 2005: The Standing Committee of the 10th NPC completely revises the Securities Law. Derivatives are regulated for the first time and a sponsorship system is included in the IPO issuance system.
Jan 1, 2006: The Securities Law comes into effect.
Oct 30, 2009: The China Securities Regulatory Commission approves a move to establish the growth enterprise board at the Shenzhen Stock Exchange. This was brought in to improve the multi-level capital market.
March 31, 2012: The CSRC releases a draft for IPO issuance reform. This involves transforming the examination and approval system into a registration system.
June 9, 2013: The Standing Committee of the NPC revises the Securities Law, removing approval for securities companies to change corporate form.
April 20, 2015: The Standing Committee of the 12th NPC reviews the latest draft of revised Securities Law.


Go to Forum >>0 Comment(s)